What is the market overview and industry significance of the Industrial Diamond Market?
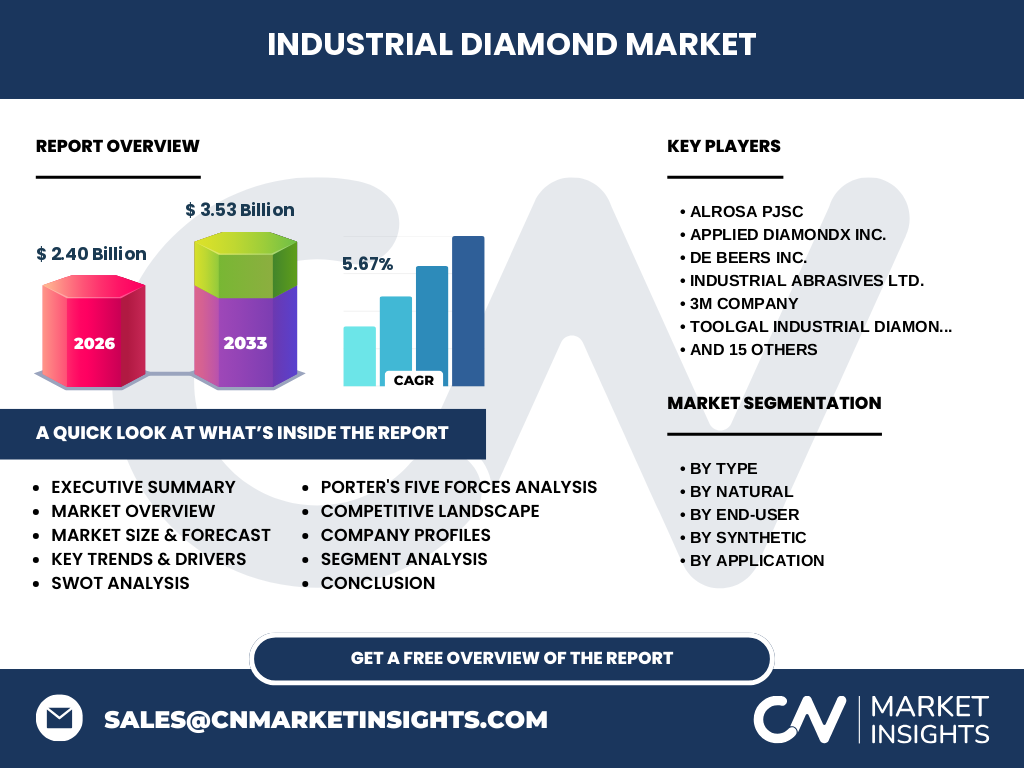
Our analysis indicates the Industrial Diamond Market represents a critical foundation for modern manufacturing, achieving a valuation of $2.40 Billion. Based on our research, these superabrasives are indispensable for extreme-tolerance machining, electronics fabrication, and heavy resource extraction where conventional materials fail.
Key market drivers, restraints, challenges, and opportunities shaping the Industrial Diamond Market
The data suggests exponential demand in semiconductor manufacturing acts as a primary growth catalyst. However, strict environmental regulations on mined carbon and geopolitical supply chain bottlenecks remain severe restraints. Opportunities heavily favor synthetic diamond innovators overcoming high-energy production thresholds.
Emerging trends and growth patterns in the Industrial Diamond Market
The shift toward Chemical Vapor Deposition (CVD) technology is transforming the landscape by enabling defect-free diamond wafers for thermal management. Industry trends show end-users prioritizing synthetic grades over natural equivalents due to consistent scalability and tailored purity.
COVID-19 impact analysis and recovery trajectory
Pandemic-induced supply chain fractures temporarily stalled industrial output across automotive and construction sectors. Recovery has been robust, driven by aggressive stimulus investments in high-tech manufacturing hubs and accelerated adoption of automated cutting tools.
Competitive benchmarking and strategic dynamics
Market concentration is high, featuring dominant multinational players like Element Six UK Ltd. and De Beers Inc. Our analysis reveals competitive advantages stem from proprietary HPHT press technologies and robust patent portfolios protecting high-purity synthesis.
Executive summary of key findings
High-level synthesis shows the Industrial Diamond Market is positioned for steady expansion, fueled by technological breakthroughs in electronics and thermal management. Strategic positioning requires pivoting toward specialized synthetic grades to capture high-margin end-user segments.
Market forecast and growth projections from 2027 to 2033
Our research forecasts the market to reach $3.53 Billion by 2033, expanding at a compound annual growth rate of 5.67%. This trajectory reflects sustained demand from semiconductor fabrication and precision machining applications worldwide.
Segmentation analysis across product types and end-users
The market is divided into Natural and Synthetic types, with synthetic variants further split into High-Pressure High-Temperature (HPHT) and Chemical Vapor Deposition (CVD). End-user verticals encompass construction, mining services, stone cutting, and machinery manufacturing.
Regional market analysis and geographic distribution
Geographic performance varies significantly, with Asia-Pacific leading in consumption due to massive machinery manufacturing output in China and South Korea. North America follows closely, driven by advanced semiconductor fabrication and aerospace machining requirements.
In-depth regional review of key markets
Regional evaluation highlights Henan Huanghe Whirlwind Co. Ltd. and Zhongnan Diamond Co. Ltd. anchoring Asia-Pacific dominance through large-scale HPHT production capacity. Meanwhile, European markets focus heavily on high-end CVD diamond applications for specialized research and electronics.
Company profiles and strategic positioning
Leading entities such as Sandvik AB, Saint-Gobain S.A., and 3M Company leverage vertical integration to secure raw material supply chains. Specialized innovators like Scio Diamond Technology Corporation focus exclusively on optical and electronic-grade CVD diamonds.
Porter's Five Forces analysis of competitive pressures
Bargaining power of buyers remains moderate due to customized tooling requirements. Threat of substitutes is remarkably low given diamond's unmatched hardness and thermal conductivity, though high capital requirements for synthesis elevate barriers to entry.
SWOT analysis of the Industrial Diamond industry
Strengths include extreme material durability and diverse application potential. Weaknesses involve high energy consumption during production. Opportunities lie in electric vehicle electronics, while threats stem from tightening trade restrictions on raw graphite and metal catalysts.
Value chain analysis from raw materials to end-users
The value flow begins with raw carbon sourcing and specialized metal catalysts, moving through capital-intensive HPHT or CVD synthesis. Processed diamonds are then integrated into grinding wheels, drill bits, and semiconductor heat sinks before reaching industrial end-users.
Investment insights and high-potential areas
Strategic recommendations emphasize capital allocation toward CVD diamond technology for thermal management in 5G infrastructure. High-potential areas include partnerships with semiconductor manufacturers seeking ultra-pure diamond substrates for high-power electronics.
Conclusion and key takeaways
The Industrial Diamond Market offers compelling growth for stakeholders prioritizing technological innovation over commodity volume. Companies mastering scalable synthetic production will capture disproportionate market share through 2033.
Research methodology and data triangulation
Baseline estimates are triangulated by combining customs trade registries, primary stakeholder interviews with executives at firms like Iljin Diamond Co. Ltd., and secondary macroeconomic indicators from global manufacturing output indices.
Scope of the report and coverage parameters
This report covers global revenue estimations, volume shipments, and technological evaluations across natural and synthetic segments from 2026 through 2033. Regional evaluations span North America, Europe, Asia-Pacific, and Rest of World.
Recent developments, partnerships, and strategic moves
Recent industry activity features aggressive R&D investments by Applied DiamondX Inc. and strategic joint ventures between electronics manufacturers and diamond producers to secure captive supply chains for next-generation power semiconductors.